What Is Banking-as-a-Service?
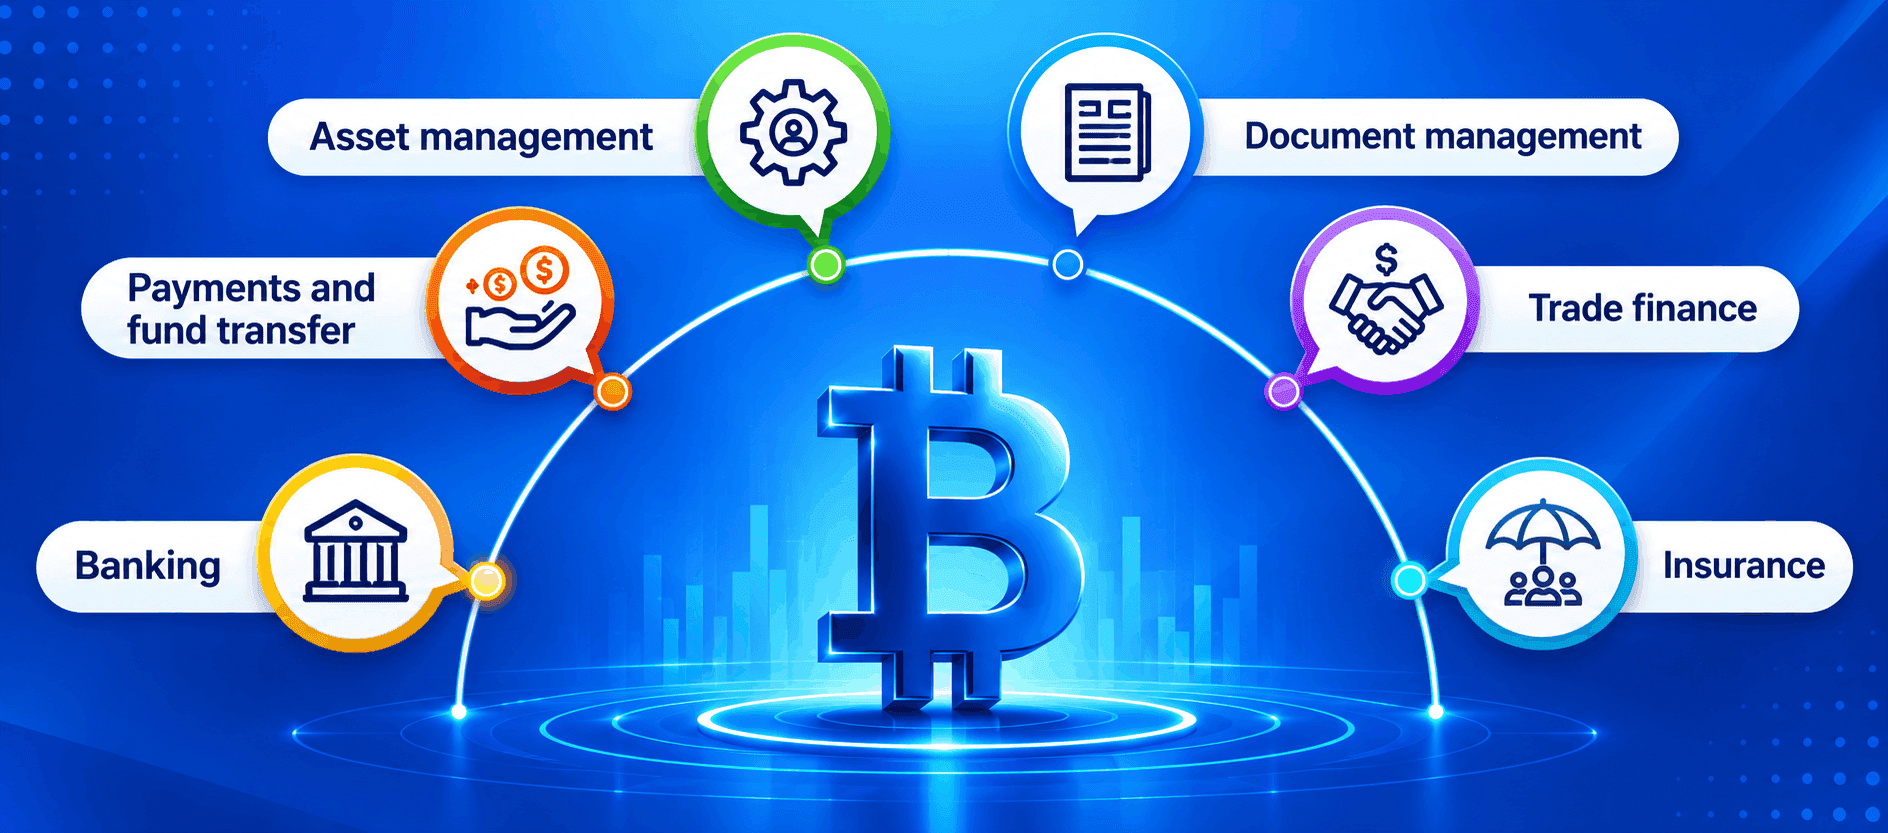
Banking-as-a-Service is a model that allows non-bank businesses to integrate banking or financial capabilities into their own products. A BaaS arrangement may involve a regulated bank, fintech company, processor, program manager, payment provider, and technology platform working together behind a single customer-facing application.
For example, a business management platform could offer customers business accounts and payment cards without becoming a traditional bank itself. The application owns much of the customer experience, while the underlying financial infrastructure is provided through regulated partners and specialized technology services. The exact responsibilities depend on the structure of the program.

How Does a BaaS Platform Work?
A BaaS platform generally acts as the technology and integration layer between a business and financial infrastructure. APIs can expose capabilities such as account creation, balance information, payments, card management, transaction data, and other financial workflows. The application can then build these capabilities into its own web or mobile experience.
The architecture can include several parties rather than one provider doing everything. A partner bank may provide regulated banking services, while a BaaS platform handles APIs, orchestration, account workflows, reporting, or integration with processors. This makes role definition and operational ownership extremely important when designing a B2B financial product.
The Role of Partner Banks in BaaS
Partner banks are an important part of many BaaS models because the financial services being offered may involve regulated banking activities. The bank and fintech need a clear operating model that defines responsibilities for customer onboarding, transaction monitoring, complaints, disclosures, data, security, and other compliance activities.
The technology company should not treat the partner bank as simply an infrastructure vendor. The relationship involves ongoing due diligence, monitoring, contractual responsibilities, operational controls, and escalation procedures. U.S. banking regulators have specifically emphasized risk management around bank relationships with fintech and other third parties.
BaaS Compliance Rules Businesses Need to Understand
BaaS compliance rules depend on the products, jurisdictions, customers, and responsibilities involved. A program may need to address areas such as customer identification, anti-money-laundering controls, transaction monitoring, consumer protection, privacy, information security, recordkeeping, complaint handling, and applicable payments requirements.
One important principle is that outsourcing a banking activity does not automatically outsource regulatory responsibility. U.S. federal banking agencies have stated that a bank's use of third parties does not diminish its responsibility to comply with applicable laws and regulations. This makes governance, documentation, monitoring, and clear allocation of responsibilities central parts of a BaaS program.
| Area | What Businesses Should Consider |
|---|---|
| Customer onboarding | Identity verification, eligibility, and account-opening controls |
| AML and financial crime | Transaction monitoring, suspicious activity controls, and risk assessment |
| Consumer protection | Clear disclosures, complaint handling, and applicable consumer rules |
| Data security | Access control, encryption, monitoring, and incident response |
| Third-party risk | Due diligence, contracts, monitoring, and contingency planning |
| Recordkeeping | Accurate transaction and customer records with appropriate retention |
FDIC Regulations and Deposit Protection in BaaS
FDIC considerations become especially important when a BaaS program involves deposit products offered through a bank. Businesses should not assume that using a banking API automatically means every customer balance has the same insurance treatment. The structure of the deposit relationship, the insured depository institution, account ownership, disclosures, and applicable requirements all matter.
For B2B products, the customer-facing company should clearly understand how deposits are held, how records are maintained, what the partner bank is responsible for, and how insurance-related information is communicated. The bank-fintech relationship should be designed so that operational processes and customer communications match the actual legal and banking structure.

Fintech Risk Orchestration in a BaaS Architecture
Fintech risk orchestration is the process of coordinating multiple risk and compliance controls across the customer lifecycle. Instead of relying on a single check, a platform may combine identity verification, device intelligence, transaction monitoring, fraud detection, sanctions screening, behavioral signals, and account-level risk scoring.
A strong architecture keeps these controls connected to the transaction and account lifecycle. For example, a new customer may receive stricter onboarding checks, while an established customer with unusual transaction behavior may trigger additional monitoring. The exact controls should be based on the product's risk profile and applicable requirements rather than simply adding every available vendor.
Technology Architecture Behind BaaS Platforms
A modern BaaS technology stack commonly includes an API gateway, authentication services, customer and account services, payment integrations, ledger or transaction systems, databases, event processing, monitoring, and external financial providers. APIs provide the connection between the business application and the underlying financial capabilities.
Event-driven architecture can also be useful for financial workflows. An account event might trigger notifications, transaction monitoring, analytics, reconciliation, or downstream business processes. Because financial systems require accuracy and traceability, idempotency, audit logs, authorization, reconciliation, and failure handling should be designed into the platform from the beginning.
BaaS Use Cases for B2B Businesses
BaaS can support many business models beyond consumer banking. SaaS companies can embed payments or financial accounts into business workflows. Marketplaces can build payment experiences around buyers and sellers. Payroll platforms can add financial services around employee payments, while vertical software companies can integrate financial capabilities into industry-specific products.
The strongest use cases usually connect financial services to an existing business workflow. Instead of asking customers to leave the application and manage financial tasks somewhere else, the product can place relevant financial actions directly inside the experience they already use.
How to Evaluate a BaaS Provider
Choosing a BaaS provider requires more than comparing API documentation and pricing. Businesses should evaluate the provider's partner-bank structure, supported products, geographic coverage, compliance capabilities, security controls, operational resilience, reporting, developer experience, and approach to incident management.
It is also important to understand what happens when something goes wrong. Ask who handles customer complaints, transaction disputes, compliance escalations, reconciliation issues, outages, and termination of the partnership. A provider that looks attractive during development can create operational problems later if these responsibilities are unclear.
Build a B2B Financial Product Around the Right Architecture
Banking-as-a-Service can make financial capabilities available inside products that were never traditional banks. But the technology is only one part of the equation. Partner-bank responsibilities, compliance processes, risk controls, customer experience, security, transaction accuracy, and operational ownership all need to work together.
If you are planning a fintech platform, digital banking product, payment-enabled SaaS application, or embedded finance experience, Web Squalix can help create a custom web and mobile solution around your business requirements. From customer-facing applications and financial workflows to API integrations and secure digital experiences, the solution can be designed around your product goals and operational needs.
Daniel is a Senior Software Engineer specializing in designing, developing, and delivering scalable, reliable software solutions. He works closely with cross-functional teams to solve complex technical challenges and build high-quality products that align with business goals.